
Introduction
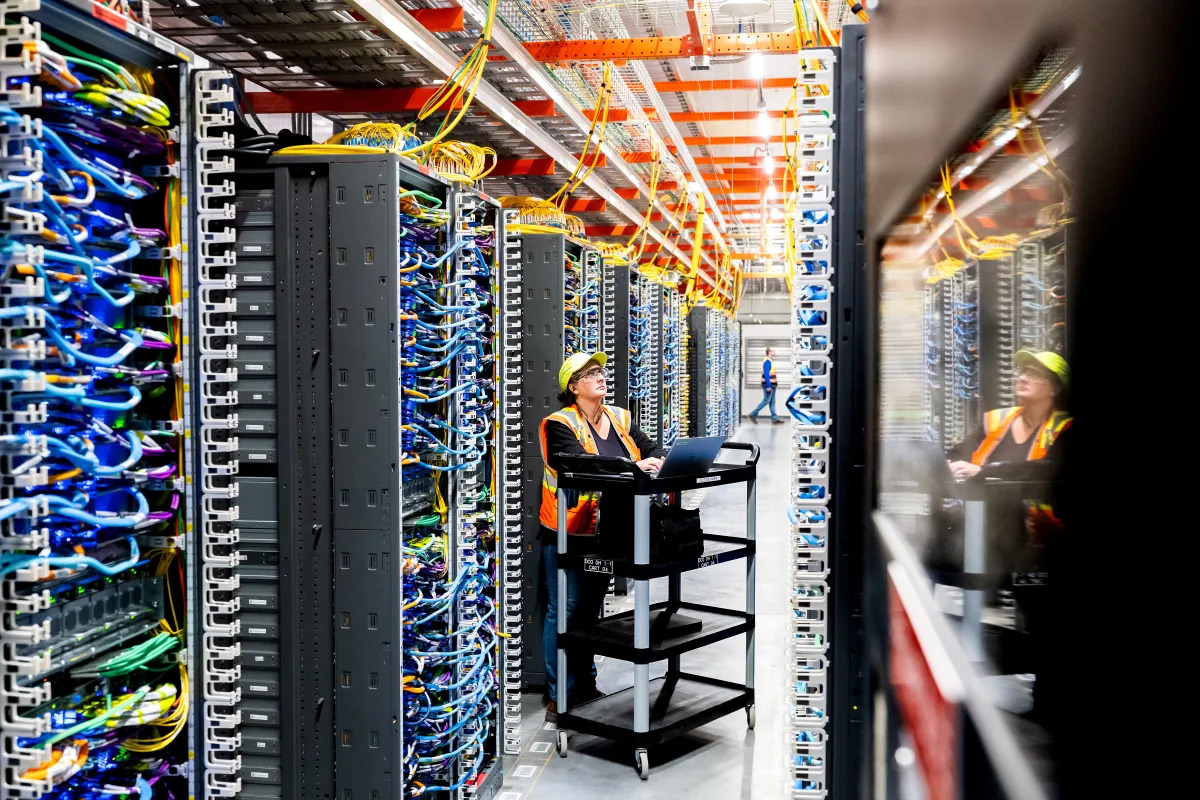
In September 2026, the American AI industry is confronting an increasingly urgent reality: the data centers are being built, but the power isn’t there to run them.
This isn’t a hypothetical concern. Moody’s estimates that roughly $110 billion in new generation investment is needed to meet U.S. data center demand. By 2030, American data centers are expected to consume 426 terawatt-hours annually. The problem is that data centers can be built relatively quickly, while power plants and transmission networks face permitting, equipment procurement, and supply chain delays—some power projects are running as much as seven years behind schedule.
This speed mismatch is now hitting the AI industry from multiple directions and has quickly become a political issue ahead of the 2026 midterms.
The House Passed the Ratepayer Protection Act 417-3: Data Centers Must Pay Their Own Way
On September 16, 2026, the U.S. House of Representatives passed the Ratepayer Protection Act by a vote of 417 to 3. The bill would require state utility regulators to establish special rules ensuring that data centers bear the costs of new generation, transmission lines, and other grid upgrades—rather than passing those costs on to ordinary residential customers.
The vote itself tells the story. In a year when bipartisanship is nearly nonexistent, a 417-3 margin means the data center power issue has crossed party lines.
Why Voters Care
The numbers are stark. On one grid covering 67 million users—including the swing state of Pennsylvania and the Senate battleground of Ohio—data center demand growth pushed costs up by $9.3 billion in a single year, a 174% increase.
Ohio Republican Senator Jon Husted has been pressing the Senate to move quickly on the bill, but he acknowledges that fast-tracking it may be difficult. Husted is facing a tough re-election fight in Ohio against Democrat Sherrod Brown, who has seized on Husted’s earlier support for data centers.
Texas Republican Governor Greg Abbott has frozen new projects while officials study the impact of data centers on power and water. New York has imposed a one-year moratorium on new hyperscale data centers.
It’s Not Just About Electricity Bills
The backlash extends well beyond power costs. In Brazoria, Texas, resident Melissa Burnett told Agence France-Presse that a 17-megawatt facility near her home sounds “like a freight train coming at you forever.” Water consumption, pollution, noise, and tax breaks for wealthy tech companies have all become local flashpoints.
In at least 20 races across 18 states, candidates have aired TV ads mentioning data centers, split almost evenly between Democrats and Republicans.
AI Companies Can’t Wait for the Grid—So They’re Building Their Own Power
Faced with the slow pace of grid expansion, major U.S. tech companies are shifting from waiting for utilities to investing directly in power generation.
Google’s BYOP Strategy
On September 9, 2026, Google announced a €13 billion investment in Finland over the next two years, including new data centers, digital infrastructure, and clean energy projects. At the same time, Google signed a 22-year power purchase agreement with Finland’s Fortum, securing up to 50% of the output from the Loviisa nuclear plant. It was Google’s first nuclear power deal outside the United States.
The industry calls Google’s approach BYOP—Bring Your Own Power. Previously, Google signed a 25-year PPA with NextEra Energy to restart an Iowa nuclear plant and partnered with Kairos Power to deploy small modular reactors starting in 2030, targeting up to 500 MW of new nuclear capacity by 2035.
Microsoft, Meta, and Amazon’s Nuclear Push
Microsoft signed a 20-year PPA with Constellation Energy to support the restart of an 835 MW nuclear unit at Three Mile Island in Pennsylvania. Reports suggest Microsoft plans to expand its global data center capacity to roughly 38 GW by 2032—more than triple its current footprint.
Meta announced partnerships in January with Vistra, TerraPower, and Oklo, alongside its earlier Constellation agreement, supporting up to roughly 6.6 GW of nuclear capacity by 2035.
Amazon invested $500 million in small modular reactor company X-energy, with plans to deploy more than 5 GW of next-generation small nuclear reactors in the U.S. by 2039. AWS also reached an agreement with Talen Energy to secure up to 1.9 GW of existing nuclear output from the Susquehanna plant in Pennsylvania for nearby data centers.
Behind-the-Meter Power as a Bridge
Nuclear solves the long-term baseload problem, but AI data center expansion can’t wait years. According to SemiAnalysis, there are roughly 75 GW of firm behind-the-meter power orders globally for AI compute, with about 20 GW of that originating in the second quarter of 2026 alone. Natural gas generation and energy storage solutions are quickly moving into large-scale AI infrastructure projects.
The $110 Billion Grid Investment Gap
Moody’s assessment shows that expanding generation alone won’t solve the power shortage. The firm notes that transmission network investment must advance in parallel to deliver power to where data centers are concentrated. Expanding transmission can also help bring cheaper power from outlying regions into rural areas.
Canada’s Saskatchewan province has already introduced policies requiring large data center operators to provide their own power supply. This reflects a broader trend: local governments and regulators are shifting the responsibility for power supply from the public grid to data center operators.
The Trump administration’s “ratepayer protection pledge” aims to prevent data center expansion from passing electricity costs onto ordinary consumers. Google, Microsoft, Meta, Oracle, xAI, OpenAI, and Amazon have all signed the voluntary pledge.
Moody’s emphasizes that data center operators must also actively participate in grid expansion to complete their facilities on schedule. The core of AI infrastructure competition is expanding from “who can get more GPUs” to “who can secure a stable power supply.”
SK Hynix and Intel in Talks: U.S. Memory Production
In semiconductor manufacturing, a report drew widespread attention. Reuters reported on September 16 that SK Hynix is in talks with Intel. While details remain limited, the discussions come amid a broader push to expand U.S. memory chip production.
SK Hynix already broke ground in August 2026 on a $3.87 billion** advanced packaging facility in West Lafayette, Indiana—the largest single development project in Indiana’s history. The facility will produce High Bandwidth Memory for AI accelerators, with mass production targeted for the second half of 2029. It is supported by up to **$458 million in CHIPS Act grants and $500 million in federal loans.
The talks with Intel suggest SK Hynix may be exploring additional U.S. manufacturing capacity, potentially leveraging Intel’s existing fab infrastructure. No deal has been announced.
What This Means
The AI power crisis is forcing a fundamental rethinking of how AI infrastructure is built. For years, the constraint was chips. Now it’s electricity.
The House’s 417-3 vote signals that politicians in both parties see rising electricity bills as a political liability. The tech industry’s response—building its own power plants, signing long-term nuclear contracts, and investing in behind-the-meter generation—reflects a recognition that the grid cannot scale fast enough to meet AI demand.
The $110 billion investment gap is a problem, but it’s also an opportunity. Companies that can secure reliable, affordable power will have a structural advantage in the AI race. Those that can’t will find themselves constrained—not by compute, but by the electricity needed to run it.







No responses yet