
Introduction
The U.S. semiconductor industry is experiencing an investment surge unlike anything seen in decades. According to Bill Frauenhofer, Executive Director for Semiconductor Innovation and Investment at the U.S. Department of Commerce, the U.S. chip program now covers 49 projects across 23 states, with approximately $750 billion in semiconductor investment flowing into the country when accounting for CHIPS Act incentives and trade agreements .
Commerce Secretary Howard Lutnick has put the figure even higher, stating that the U.S. has secured $1.2 trillion in investment commitments for semiconductor manufacturing, with the goal of increasing America’s share of global chip production from less than 2% to 40-50% .
“We started at less than 2% of global semiconductor production. We are now moving toward 40%. If Intel succeeds—and I believe it will—we will hit 50% by the time we leave,” Lutnick said .
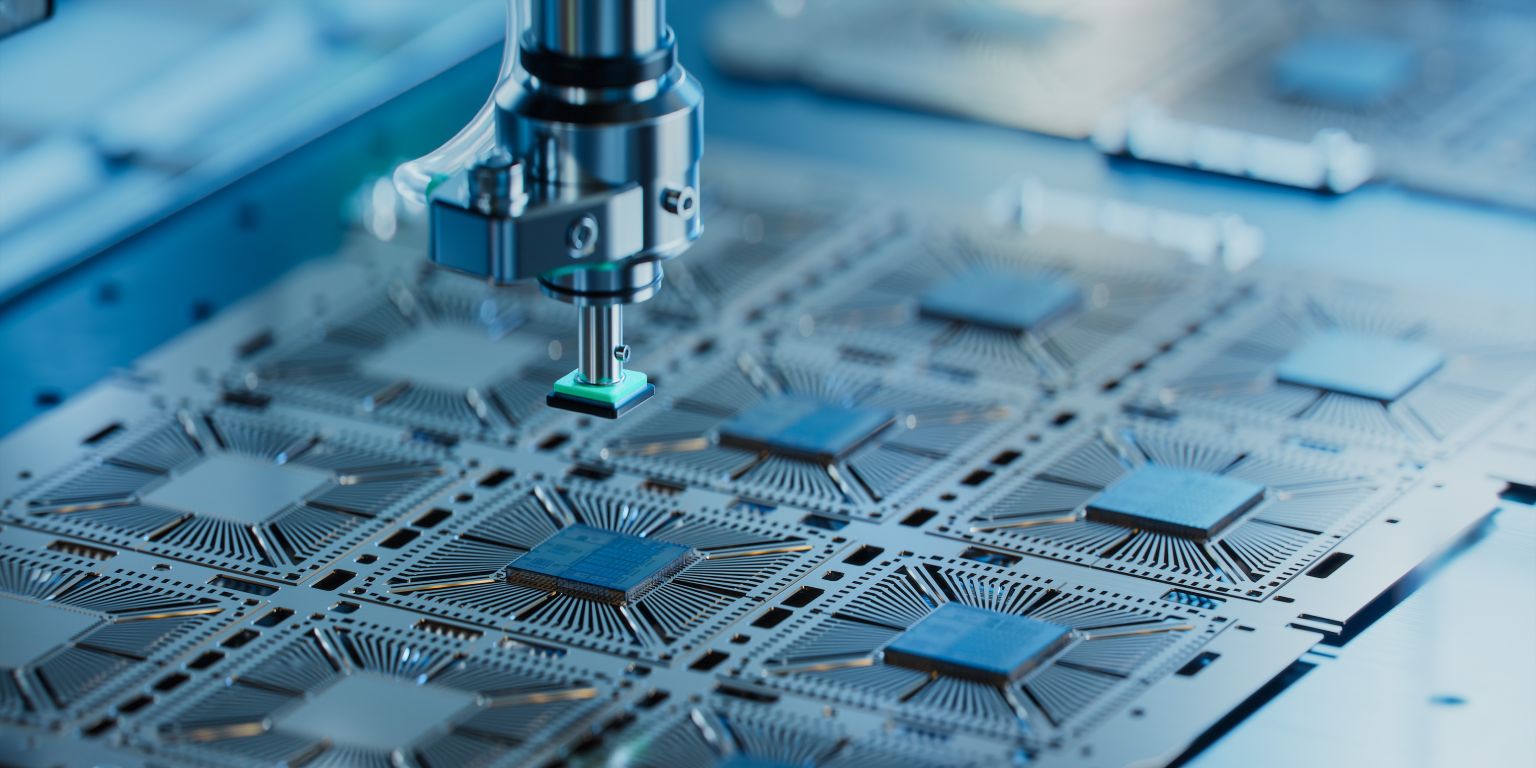
The investments span the entire semiconductor supply chain—from wafer fabrication to advanced packaging, from HBM memory to the specialty chemicals and components that make chip manufacturing possible.
TSMC: The Largest Foreign Investment in U.S. History
TSMC has committed to a record $265 billion investment in the United States, making it the largest foreign direct investment in American history .
The investment will fund 12 facilities in Arizona, including leading-edge semiconductor fabrication plants and advanced packaging facilities. In July 2026, TSMC announced an additional $100 billion on top of its previous commitments, citing “strong multi-year demand from our leading U.S. customers” .
“This investment will further foster the development of the U.S. semiconductor ecosystem, strengthen the supply chain, and support significant job creation,” said Dr. C.C. Wei, TSMC Chairman and CEO .
The TSMC investment is part of a broader U.S.-Taiwan trade and investment deal that is expected to catalyze an additional $250 billion in direct investments by Taiwanese semiconductor and other enterprises in the United States .
SK Hynix: First HBM Production Facility in the U.S.
In August 2026, SK Hynix broke ground on a $3.87 billion advanced packaging facility in West Lafayette, Indiana—the largest single development project in Indiana’s history .
The facility will produce High Bandwidth Memory (HBM), the critical memory technology that powers AI accelerators from Nvidia, AMD, and others. This will be the first HBM production facility on U.S. soil, with mass production targeted for the second half of 2029 .
SK Hynix CEO Kwak Noh-jung called the Indiana project “the first supply hub for ‘Made in USA HBM'” and said it would contribute to strengthening the U.S. semiconductor supply chain for both economic and security purposes .
The project is supported by up to $458 million in CHIPS Act grants** and **$500 million in federal loans. It will also house next-generation HBM research and development, with a workforce expected to reach approximately 1,000 employees .
The $874 Million AI Computing Investment: Targeting Bottlenecks
Beyond manufacturing, the Commerce Department is targeting the specific bottlenecks that limit AI computing performance. In July 2026, the department signed letters of intent with seven companies for $874 million in R&D funding under the CHIPS and Science Act .
The investments focus on three critical AI computing challenges: data transmission, memory access, and chip integration .
GlobalFoundries received the largest award—up to $300 million—for co-packaged optics technology that uses light instead of electrical signals to transmit data between chips. The Commerce Department believes this could advance U.S. leadership in AI infrastructure by two to three years .
Kepler Computing received up to $245 million** for ferroelectric memory technology that addresses the “memory wall” problem in AI systems. **Multibeam Corporation** received up to **$140 million for advanced packaging technology that enables Chiplet designs .
The remaining awards went to Extropic ($75 million for thermodynamic computing), Thintronics ($50 million for low-loss dielectric materials), OBSIDIA Semiconductors ($34 million for counterfeit detection), and Aeluma ($30 million for photonic substrates) .
Notably, the government will receive minority, non-controlling equity stakes in each company—a departure from traditional one-way subsidies .
The Global Semiconductor Market: $1.6 Trillion in 2026
These U.S. investments are happening against a backdrop of explosive global semiconductor growth. According to Gartner, worldwide semiconductor revenue is expected to reach $1.6 trillion in 2026, a 92% increase from 2025 .
Memory is the primary driver of this growth. Memory revenue is forecast to reach $837 billion in 2026, accounting for 54% of total semiconductor revenue—up from 27% in 2025. DRAM revenue is expected to increase 246.6%, while NAND flash revenue could grow 371.9% .
“The pace of the semiconductor industry expansion is accelerating dramatically, driven by sustained investment in AI infrastructure and a stronger-than-anticipated memory pricing cycle,” said Ben Lee, Director Analyst at Gartner .
The AI data center ecosystem is expected to grow from 36.5% of semiconductor revenue in 2026 to more than 53% by 2030, underscoring a structural shift in where semiconductor value is created .
The Supply Chain Challenge: Beyond Wafer Fabs
One of the key insights from the U.S. semiconductor program is that building wafer fabs alone is not enough. As Frauenhofer noted, the semiconductor supply chain encompasses minerals, specialty chemicals, fluids, and countless components—and any single missing element can become a bottleneck .
The U.S. is working to attract suppliers from Taiwan, Europe, and other partner nations to establish operations near their customers in America. The goal is to create an “easy button” for companies considering U.S. investment .
“The U.S. doesn’t just need to inventory domestic supply capacity. It also needs to identify which materials can be provided by trusted partners and build a more complete risk diversification mechanism,” Frauenhofer said .
This approach recognizes that no single country can build a 100% self-sufficient semiconductor supply chain. Instead, the strategy focuses on reducing critical vulnerabilities while maintaining access to global expertise and materials .
Conclusion
The U.S. semiconductor investment boom represents one of the largest industrial policy efforts in American history. With $750 billion to $1.2 trillion in investment commitments, 49 projects across 23 states, and a goal of reaching 40-50% of global chip production, the scale of the effort is unprecedented.
The strategy goes beyond wafer fabrication to target the entire supply chain—from advanced packaging and HBM memory to the specialty materials and components that make chip manufacturing possible. The government’s willingness to take equity stakes in funded companies adds a new dimension to industrial policy, ensuring that taxpayers share in the upside of successful investments.
The question is whether this coordinated push will be enough to secure American leadership in semiconductors for decades to come. The early signs suggest significant progress—but the industry remains dependent on global supply chains, and the gap between investment commitments and actual production capacity remains substantial.







No responses yet